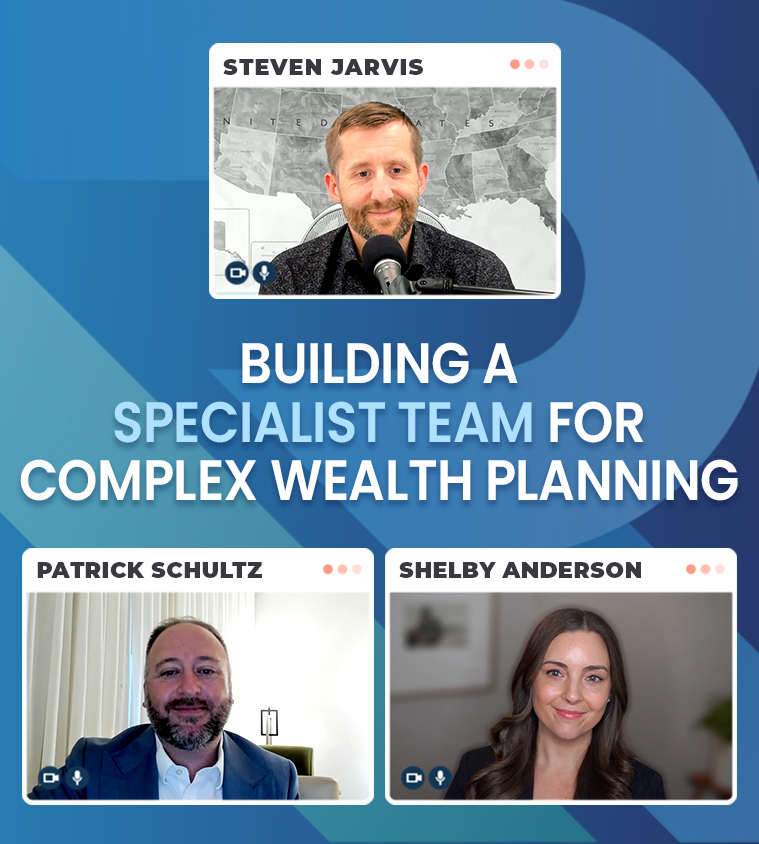
Building a specialist team for complex wealth planning with Patrick Schultz and Shelby Anderson
Steven Jarvis,CPA is joined by Patrick Schultz and Shelby Anderson of Clark Capital Management Group to discuss how financial advisors can use specialists to serve clients with complex wealth planning needs. Patrick and Shelby explain how their work in estate planning, business succession, charitable giving, and wealth transfer complements an advisor’s financial plan. They share why business owners should start preparing for an exit three to five years in advance and how missing the implementation steps can undermine an estate plan. The conversation also covers questionable tax strategies, nondisclosure agreements as a warning sign, and the value of setting clear expectations among advisors, attorneys, and CPAs. They emphasize building a team that puts the client’s outcome first.
Steven and his guests share more tax-planning insights in today’s Retirement Tax Services Podcast. Feedback, unusual tax-planning stories, and suggestions for future guests can be sent to advisors@rts.tax.
Are you interested in content that provides you with action steps that you can take to deliver massive tax value to your clients? Then you are going to love our powerful training sessions online. Click on the link below to get started on your journey:
Retirementtaxservices.com/webinars
Thank you for listening.
Steven Jarvis, CPA (00:49.875)
Hello everyone and welcome to the next episode of the Retirement Tax Services Podcast, Financial Professionals Edition. I’m your host, Steven Jarvis, CPA. And on this week’s episode, I have a couple of guests joining me to explore how specialists can help financial advisors do more for their clients, how we build great relationships and make sure we are answering clients’ questions even when they are outside of our core area of expertise. So joining me this week, Patrick Schultz and Shelby Anderson from Clark Capital Management Group. Welcome to the show.
Patrick Schultz (01:20.916)
Thanks, Steven.
Shelby Anderson
Thank you.
Steven Jarvis, CPA (01:22.125)
I hate to do a disservice by introducing people incorrectly. So I’ll give you each a quick chance to say, here’s my background. Here’s my area of expertise. Here’s why someone should listen to me. So Shelby, ladies first, why don’t you go ahead?
Shelby Anderson (01:32.416)
I’m Shelby Anderson. I am an estate planning attorney and tax attorney by way of background. And my role today is a senior wealth planner at Clark Capital Management Group.
Steven Jarvis, CPA (01:42.708)
Awesome. Welcome, Patrick.
Patrick Schultz (01:44.083)
Patrick Schultz, almost the exact same background. So I’m an estate planning tax attorney by trade. And now I run the team and I’m a senior wealth planner at Clark Capital Management Group. All of us have almost the exact same background, which is great. You get to deal with people who all they do is the really nerdy stuff in life.
Steven Jarvis, CPA (02:03.916)
Yeah. Well, you are my kind of people then. I am proudly a tax nerd as well as other kinds of nerds, but we’ll focus on tax and wealth planning today. I feel like as I’ve kind of grown into this industry more, because I’m not a financial advisor originally, there is a lot of terminology that we use that sometimes we take for granted that a client may or may not understand what we mean. And most of the time they have no idea what we mean. So let’s start by talking really specifically about what you mean by wealth planner, because you’re using that very specifically. There’s a reason you’re not saying financial planner, and it’s not just because you looked up a list of synonyms and said, I don’t want to sound like everybody else. You’re doing something different. So what do you mean by wealth planner?
Patrick Schultz (02:40.125)
So it’s kind of a broad term, but generally we’re talking about estate planning, wealth transfer, charitable giving, concentrated stock positions, equity, executive comp, and then clients going through liquidity events. What it’s specifically not is coming up with a financial plan.
Steven Jarvis, CPA (02:55.750)
I love that because one of my first red flags for a new service professional I’m meeting is when they can’t tell me who they’re not a fit for. I love it when people just lead with and here’s what I’m not good at, because that helps us narrow the conversation. And so really, you have very specifically said, here’s all these complicated areas that are relevant to wealth in certain situations, but that aren’t your typical financial plan of, you know, a lot of financial advisors will think of financial planning as kind of these five pillars of estate, investment, taxes, risk management, cash flow, kind of these different pieces. That’s kind of our base level foundational plan. For me, I come in specifically when we want to go deeper on tax planning, you’ve kind of got this whole list of, OK, we’d rather work with a financial planner who’s done the financial plan. We just want to be experts in these areas. Shelby, before we hit record, you started kind of talking about how I think similar to most consumers, your understanding of what a financial planner could be or should be has evolved over time.
Steven Jarvis, CPA (03:47.791)
So kind of talk about that journey for you of what you used to think versus what you’ve learned along the way and how you see the role of a financial advisor today.
Shelby Anderson (03:55.750)
Absolutely. So I’ll start by saying that Patrick and I both grew up in like the law firm life, right? We were practicing attorneys. So our exposure to financial advisors, financial planners was just who our clients were working with. Some were hands on and involved in meetings and going through the financial plan. Others were really hands off and didn’t have anything to do with the estate planning. They might send us some statements or a personal financial statement of a client. We put together the estate planning documents and turn clients loose. Similarly, when we completed estate plans, we would hand the client a nice funding memo of here’s how you should retitle your assets, send them on their way. And we probably wouldn’t see them again for five to 10 years, maybe for our best clients. And that was the end of our involvement. And so it was very transactional in nature. And what we saw also is that on the back end, when estates needed to be administered, I could have drafted what I thought was a very comprehensive plan.
Shelby Anderson (04:56.541)
But if it was never implemented properly, you were now administering something that may not work the way that clients thought. And so I started to see this gap. I’m not alone. The wealth planning industry has existed for some time, but I didn’t know jobs like mine existed when I was in private practice. And I didn’t know that financial planners had access to resources like Patrick and myself and other wealth planners who were there to help bridge that gap and make sure that clients are getting that comprehensive planning.
Steven Jarvis, CPA (05:29.041)
I appreciate that description. The three of us on this podcast, we’re all specialists in these areas that touch financial planning. And when we talk about the extremes, just about anybody listening to this podcast can think of a really extreme situation where they’d say, of course, I would call a CPA, of course, I would call an attorney. I think where it’s a little bit more complicated is kind of all the stuff in between of like, how do I know when is the right time to handle this myself versus call in and pay for the expertise of a specialist? So I like to use a medical analogy because it hits home for most people of financial advisors really do serve this great role as kind of like the general practitioner that first person you go to the person who understands the most broadly about your history, your current situation. And at some point, like if we need heart surgery, of course, we want a heart surgeon. But I feel like what advisors struggle with and certainly consumers struggle with is yeah, but OK, when does the handoff happen?
Steven Jarvis, CPA (06:20.333)
When would I expect my general practitioner to call in the heart surgeon for a consult? So for wealth planning, for this list of services that you guys are talking about, like how do you help people navigate that? Because I’m sure you don’t want to call every time somebody says, now, wait, did I sign on page two or page three? Like there is a this is too simple. How do we navigate that?
Patrick Schultz (06:39.500)
And for us, as weird as it sounds, we set minimums, I will say this. There are always exceptions. You can run into clients with a million dollars that have really, really complicated lives. But typically our team is getting involved when clients have five to 10 to 20 to really big numbers of investible assets. So we’re there to help when it’s complicated. There is an acknowledgement that there’s probably an estate tax issue, whether that’s federal or whether that’s a state estate tax issue. But there’s probably some sort of estate tax issue. There might be issues related to the sale of a business. And how can they position that in a way to pay the least amount of tax? And this could be years ahead of time. It might be a client wants to give assets to a child to help them buy a home. Well, how do we do that in a way that’s going to protect the home in case the child later gets divorced? So it’s the things that come up where an adviser goes, oh, that’s interesting or oh, that’s kind of complicated.
Patrick Schultz (07:38.250)
And as you said, most advisers, they’re in the day to day of their clients, so they know what’s going on. So because they’re in the day to day, they don’t always immediately reach for their experts. But when it’s not the thing that they do all the time, that’s when they should reach for experts. The more people they have on their bench, the deeper their team is, the better for the clients and the more services the client is going to be provided and the better outcomes across the board.
Steven Jarvis, CPA (08:04.541)
Yeah, absolutely. A real big theme for us on this podcast is how do we take action? Like at the end of the day, like information is interesting. Action has value. And so like when I think about what I do with financial advisers, so we have like our premier members who are part of our community, they get access to office hours, they can get on calls twice a month with me. They’re asking specific questions, but I’m not helping with the execution in that case. So like that’s one way they get access. But we also have advisers where we’re full on doing the tax returns, we’re getting involved in the tax plans. And so we’re helping with the execution piece. We have kind of a variety of ways we step in and help advisers. What does that actually look like for you guys? Is this like, hey, if I have a question, you’ll do some hourly consulting or it’s I’m only going to do the full engagement all the way from idea to execution. Talk a little bit about how the actual business model works.
Shelby Anderson (08:48.583)
Yeah, absolutely. So Clark is an asset manager. That is our business. Patrick and I serve alongside as a service offering for clients and prospects of Clark Capital. Clark Capital serves independent financial advisers. So the goal being that we can help financial advisers who are in that independent space compete against folks like the wirehouses who have embedded wealth planning teams in house and have that deep bench of experts. So all access for us is through financial advisers and financial planners. We don’t let clients come to us directly either to invest or to work with our wealth planning team. But by that same account, we’re not charging hourly rates. We’re not charging planning fees. This is all a part of the asset management piece of Clark Capital. So the fees that clients pay for our asset management cover the cost of Patrick’s and my services.
Steven Jarvis, CPA (09:49.083)
Got it. So then like, again, just kind of practically here, do you see more advisers coming to you? Obviously, they’re going to come to you because they see this this menu of services. They’re not seeing it other places. But are they coming to you when they have a specific complicated issue come up and then that’s where the asset management starts or it’s more of like the advisers are seeing they have more and more clients in this this investment range where they know this is going to become relevant someday. And so they start with the asset management and then the services come in later. Like what do you see in practice or is it a mixture of the two?
Patrick Schultz (10:16.416)
It’s a mixture of the two. We see we’ve got a lot of clients who use Clark. So Clark is considered a high net worth asset manager. Meaning our target kind of clientele are people who have a million dollars or more. Now there are people who have less. That’s kind of million dollars or more investing in Clark. And we don’t generally get involved until the client’s got five million six ten whatever the case may be. It’s a larger number. So a lot of advisers may have worked with Clark for years and now they run into their first really big case. And we have we call them investment consultants. They are wholesalers who are out in the markets and they’re the ones who are really interacting with the advisers on a day to day basis. And when a case comes up they might say to the adviser, you know, you should bring in our wealth planning team. It doesn’t cost anything. Let’s talk about how we can help that client. And the advisers a lot of times they don’t know that they have access to it because their lives are busy.
Patrick Schultz (11:06.833)
They’re doing a million different things and they forget about the service or they just have never had something come up. So we have to introduce them. Here’s what we can do now with our big limitation. The thing we don’t do, we don’t draft documents. So I know you said that you do tax returns. We don’t draft documents anymore. We’re architects, our joke is we’re architects We are not general contractors. When it comes to execution that side we’ll work with their CPA out in the field. We’ll work with their attorneys to make sure the documents are drafted and done the way we want. We’ll review things. We’ll make sure it is the plan that we want. But it also means that we get to be engaged with clients in a different way. As Shelby said earlier in private practice, you’re super transactional. We don’t get to be super transactional. We get to be consultative. It’s a lot more fun to be consultative. Just sit down with a client and say, tell me what’s important. Like, what do you want to have go on with your life?
Patrick Schultz (11:57.500)
Let’s talk about how your wealth should serve you and your family.
Steven Jarvis, CPA (12:00.416)
Yeah. I mean, similar to how most financial advisers charge anymore. Like this isn’t like there isn’t that incentive to like we have to come up with this big complicated strategy because that’s the only way I get paid. It’s wrapped into what you’re doing. And again, I appreciate that you’re you’re just transparently saying here. Here are things we don’t do. I wish that was easier to get to sometimes of like, I don’t need you to do all the things I just need to understand what it is you do really well and what it is that you don’t do. That’s really interesting. So you guys have a lot of experience with this. So whether it’s an adviser worked with Clark or someone else, like what are some of those things that come to mind that an adviser should be on the lookout for of, hey, my client base, my questions I’m getting are getting more complicated. It’s time for me to think about how to find resources on this. Twenty twenty seven is right around the corner. And we all know that if we want to level up in twenty twenty seven, we’ve got to be making plans now so we can hit the ground running.
Steven Jarvis, CPA (12:50.083)
That’s where our friends at BELAY come in. They connect financial advisors with vetted, finance-fluent client service assistants who can help you with every step of your process. Those things you need to delegate, those things you probably should have already delegated, but just didn’t know who to give them to. If you want twenty twenty seven to be bigger and better than ever, get with BELAY to learn about the resources they provide so you can get the resources you need to level up for your clients and to make it easy to get connected with BELAY. You can text RTS to 55123 to get that conversation started. Make twenty twenty seven the best year yet.
Shelby Anderson (13:28.041)
The complexity of clients’ lives grows as wealth grows. And so it’s watching for those kind of transitions, those major life events. Certainly one of the most glaring is if you have business owner clients and they’re thinking about business succession, especially an exit, a sale that they need to get them to retirement, that’s a prime opportunity. In fact, that’s where we see a lot of business lost for advisors is they’re not bringing in that full team, even in financial advisors and financial planners who have existing client relationships. Because you can bet that if the business sale takes place, there are going to be other advisors offering these services and calling clients as soon as the sales data is published. People watch these things and reach out proactively. And the last thing you want is for a client that you’ve worked with for years and developed that relationship with to take the business elsewhere because there’s more services being offered by someone else. So with business, I was just getting in front of them early and often on exits and letting them know that you have a team behind you of experts that you can bring in when the time is right.
Steven Jarvis, CPA (14:38.708)
Yeah, I love that example because I think too many business owners and too many financial advisors, whether they’re for themselves as business owners or for their business owner clients, they think about an exit as well. That’s something I’ll plan for when that’s relevant. But the reality is, is every business owner is going to exit their business. It’s just that not every one of them has a plan to do it. Whether hopefully that’s through something intentional, like a sale or maybe it’s even bringing your kids, like whatever it is, hopefully it’s on purpose and you have a plan and a strategy, but hate to break it to you. This is a surprise, but every single business owner is going to exit their business someday. And there are a lot of unfortunate situations where they didn’t plan ahead and life went a way they weren’t expecting. If we wait until we think we’re ready to exit to make a plan, we’ve probably missed a lot of opportunities.
Shelby Anderson (15:24.750)
Absolutely. Patrick and I say the sweet spot to get in front of folks that are going to sell is three to five years before exit. I mean, that far in advance, if you want to have the most opportunity to save on taxes, to make sure business structure is done properly, to make sure that you’re taking into account expenses, positioning the business to be in the best position to sell, getting corporate records together and documented policies and procedures. And so it’s a lot of work. And if you don’t know that someone’s planning to exit until they have an offer in hand, you’ve missed opportunities.
Steven Jarvis, CPA (15:59.875)
Yeah, absolutely. And Shelby, I really appreciate it. I want to highlight that in there, like what I didn’t hear from you was here are shiny object strategies that are going to get all of your money into the Cayman Islands so you never pay taxes. You talked about corporate documents and processes. And I don’t think you mentioned bookkeeping specifically, but that always comes to mind. I’m sure is on your list. Like those are the things that when I’m talking to business owners who like how do I maximize my valuation? Like let’s start with the basics because while you thought you were being clever by running all your personal expenses through the business, guess what? Now the person buying your business is going to try to pay way less for your company as you try to verbally explain. Oh, no, no, no, those aren’t real expenses.
Patrick Schultz (16:38.750)
I’ve seen more Corvettes owned by HVAC companies than by human beings. It’s amazing.
Steven Jarvis, CPA (16:44.250)
I just had a conversation with a client this week. They’re getting ready. They’ve had this long W-2 career. They’ve retired from that career. They’re getting ready to start as a 1099 contractor. And that very first question, I’m actually I’m getting ready this week as we’re recording this to give an in-person presentation that the whole thing is going to be TikTok tax advice fact or crap. And cars are ones that come up all the time of, hey, buy the G-Wagon. Come on, get the G-Wagon bonus depreciation all day long. And so thankfully, this I’m this client, really sophisticated guy, but but still curious, right? We come across clients. And I would imagine you guys see this in your space all the time where somebody’s heard a little bit of something. They probably don’t really understand what it is, but they want to make sure they at least ask. And so at least for this client, it was, hey, were you going to use the car exclusively for business purposes? He’s like, well, no, probably like 10 percent for business purposes.
Steven Jarvis, CPA (17:31.041)
OK, let’s not play silly games. So I mean, what are some examples for you guys of strategies that people come to you with thinking, hey, wait, I’ve got the silver bullet. Just do this for me.
Patrick Schultz (17:40.916)
There are so many that are out there. OK, TikTok is the bane of our existence. It used to be the country club dinner. It used to be the country club dinner. Well, yeah, they talked to somebody at the country club. They heard something that happened and it could have been under a different tax scheme, could have been in different interest rate environments. So many things. And they come to you and ask the question. And we have to kind of dig down to find out what the goal is. A lot of times we look at all these complicated techniques. At the end of the day, the answer is just pay the tax. Like just pay the tax. Sometimes there are great Like, for instance, we love Section 1202, the qualified small business stock. Like it is our bread and butter. It is so much fun. But you can save clients so much money. But it takes time. You’ve got to have the right business. It takes a lot of work. If somebody is approached with what I would call a scheme or something that sounds too good to be true, it probably is.
Patrick Schultz (18:36.250)
The other kind of key thing that I tell clients is if it’s tax related or legal related and somebody asks you to sign a non-disclosure agreement, it’s not something you should do. It’s just it’s not a good idea.
Steven Jarvis, CPA (18:50.041)
Well, and for people listening, let me talk about that one for just a second. So, so Patrick, you tell me if your thought on this is different. My experience, because I’ve done due diligence on so many tax strategies that get pitched to my clients, because if someone comes to one of my clients, like I’m going to do them the service of at least exploring it with an open mind. Even if right on the face of it, I’m like, this is garbage and here’s why. Like I will be open minded and I’ll try to learn something new. But I’m with you. If part of that due diligence includes a non-disclosure in the tax world, what that usually means is, hey, we’ve got a team of attorneys who have come up with this really convoluted piece together. Like here’s a PLR over here and appeal a private letter ruling is What a PLR is, that we’re going to squint at just right and tell ourselves it works until the IRS gets mad at us. And the reason we’re having you sign an NDA is not really because we don’t want our competitors selling this.
Steven Jarvis, CPA (19:39.291)
It’s because we want to delay when the IRS finds out exactly what we’re doing. And so, yeah, you signing an NDA for a tax strategy that’s based on publicly available tax code, that’s a huge red flag to me.
Patrick Schultz (19:50.958)
Huge red flag all day long, all day long. And it’s funny, most of our clients, they are the business owners. They’ve worked really hard. Yeah. If you say to them, does this feel too good to be true? Did, does it feel like somebody’s trying to sell you snake oil and they’re like, yeah, but I really want it to be true. And you’re like, I mean, yes, we all love like puppies and rainbows and all of that. But sometimes it’s just not true.
Steven Jarvis, CPA (20:14.250)
That really is a valuable service that we can provide to be that dose of reality in a constructive way because we can do a whole podcast on this. But there is an art to telling a client no in a positive way, because what you don’t want to do is when a client brings one of these crazy strategies to you, you say, geez, Patrick, that’s the dumbest thing I’ve ever heard. Why would you possibly believe that? Because then your client’s never going to ask you a question again. And maybe that sounds a little extreme and you’re thinking, well, I would never call my client dumb, but your tone can tell your client they’re dumb, your body language, like, so we got to, we got to think about these things. So let’s pivot for just a second here in the last few minutes we have and let’s talk a little bit more broadly about because we’ve been discussing really this intersection of different professionals working together to serve a common client. What are the things that you both have seen that help build constructive relationships because it can kind of naturally turn into kind of who’s smarter or who has the better idea.
Steven Jarvis, CPA (21:05.625)
So how do we build effective relationships where the client’s the one winning?
Shelby Anderson (21:09.458)
I think first and foremost is setting expectations. And Patrick and I set the expectation early that we are not drafting attorneys. We no longer work for a law firm. That’s a service we cannot provide. And that our role is not to step on the toes of attorneys or CPAs that we need a team approach and that we are there to work together with their professionals. And if they don’t have those professionals, we’re there to help them find those professionals and make sure we’re all working in the same direction. So I underscore the fact that other professionals are necessary to completing the engagement and that the expectation is, is that we will all work together. And luckily so far, I haven’t had a negative experience with a client’s attorney other than saying, look, I don’t know that this is maybe the right professional for you, especially if they’re working with a generalist who really isn’t focused on estate planning or whatever strategy we’re trying to do to tell them nicely they’ve outgrown their practitioner is about as bad of an experience as I’ve had.
Shelby Anderson (22:15.208)
And that is just a simple conversation of, look, you’re, I understand why you’ve worked for, with this attorney for years. I have nothing against this attorney. They’re welcome to still be involved in the engagement. But I think that you’ve outgrown them and that now you need somebody who specializes in more complexity. And usually the attorney is kind of relieved to be off the hook in that engagement because they don’t feel comfortable drafting some of those more complex documents anyway. And we’re giving them that out.
Steven Jarvis, CPA (22:42.166)
I love that. I tell people all the time that if we don’t set expectations, whether it’s with another professional or a client, that other person is going to make up expectations that we can never live up to. And so we have to take responsibility for setting what those expectations are. So I love that. Patrick, what else comes to mind for you?
Patrick Schultz (22:56.958)
Acknowledging that typically in most clients’ lives, their financial advisor, financial planner is like the key person. They see them the most. They’re the ones who, when they need money, they go to. There’s an issue in the family. They’re going to talk about it. Like they see them typically on a quarterly basis. Maybe it’s twice a year, but CPAs see them typically once a year at tax time, maybe signing and the attorney in practice every five years if they’re lucky, so acknowledging that the financial advisor probably knows more than anybody else is step number one. So I always try and make sure that everybody on the team, like they’ve been working together for years, but we all acknowledge like if there’s a question about what’s going on with the family, the advisor probably knows. So let’s go there first. Like we might know the books more. We might know the legal documents, but they generally know the people the most.
Steven Jarvis, CPA (23:48.041)
Yeah, that resonates with me so much, Patrick. Like, I mean, some of it speaks to what Shelby was talking about with teamwork, but that this idea of like at the end of the day, we all got to be working for the client’s best outcome or this isn’t going to work. Yeah. It just comes back to being a team player. If there’s, there’s any degree of, I feel like somebody on the call is trying to prove they’re smarter than me. Like this just isn’t the right fit. Maybe you are smarter than me. Maybe you’re not. No matter which one of us is smarter, I don’t want to work in that dynamic. Yeah. So, so that idea of setting the expectation, even with the client, it’s like, hey, we’re willing to work with anybody as long as they’re a team player. It’s great. They’re a team player. Then we’re going to work together. And then if they’re not a team player, then the, you’ve already given the client the words to opt out of, oh, wait, you mentioned that you’d work there. They’re not really a team player.
Steven Jarvis, CPA (24:24.041)
Are they? It’s time to find somebody new.
Patrick Schultz (24:25.541)
There’s a few brilliant attorneys out there and not that attorneys have egos. Of course. Yeah. That’s just not a thing. They’re really smart. They are terrible team players. They’re not the people that we’re typically working with, but there are also a ton of attorneys and CPAs who are just as smart and they get along really, really well. If we disagree with somebody, we’re not on a call. We’re not going to like turn this into a big fight. It’s going to be, let’s get together afterwards and talk and figure out if we can come up with a solution that’s great for everybody. We, again, we’re all client facing. We want to make sure the client feels supported by all of the professionals in their life.
Steven Jarvis, CPA (25:00.916)
Yeah, absolutely. Before we wrap up here for people listening who are interested in what you guys do, how do they learn more? How do they reach out? How do they get in contact?
Patrick Schultz (25:07.875)
So, Clark Capital Management Group, CCMG is kind of the internet way of things, but really talk to your advisor. So, we don’t do anything directly with end clients. Everything is through the advisor. So, if you’re interested, we have 24 for our advisors, 24 different investment consultants, again, our wholesalers across the country. There’s one in every region who would be happy to talk with them and educate them about Clark Capital.
Steven Jarvis, CPA (25:34.250)
CCMG. I love it. Well, Shelby, Patrick, thank you so much for your time. I appreciate the expertise and wisdom there. There is, there’s so much that we can do that’s not just the technicalities. It’s how do we build these relationships? How do we solve for great client outcomes? How do we identify when to ask these questions and when to ask for help? Any really great professional is going to understand what they’re great at and where they need to tag somebody in. So, appreciate your time to everyone listening. Thanks for being here. Until next time, good luck out there and remember to tip your server, not the IRS.